GST Requirements for the Freelance Gig Economy
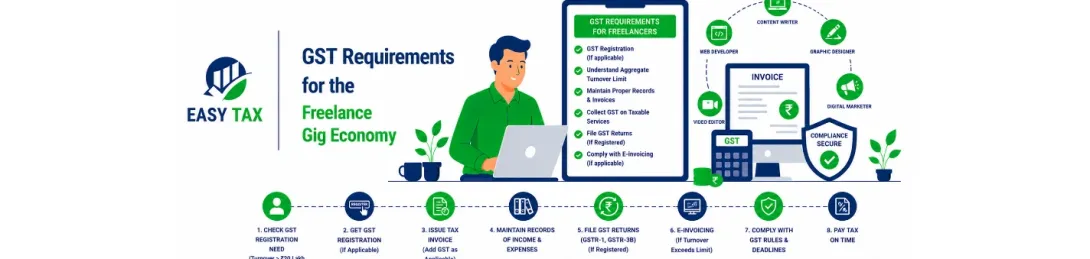
GST for Freelancers and Gig Workers in India: Registration, Rules and Compliance
Freelancers and gig workers in India earn income through independent projects, consulting assignments, online platforms and international clients. Although these professionals may not operate a traditional business, their services can still come under the Goods and Services Tax (GST) framework.
However, GST registration is not automatically compulsory for every freelancer. The requirement depends on factors such as aggregate turnover, the nature and location of services, applicable exemptions, and whether the work is supplied directly or through an e-commerce platform.
This guide explains GST registration for freelancers and gig workers in India, including turnover limits, platform-based work, foreign clients, export of services, Letter of Undertaking (LUT), Input Tax Credit (ITC) and return filing.
Jurisdiction: India. Legal framework: CGST Act, 2017, IGST Act, 2017, applicable GST Rules and notifications.
Who is a freelancer or gig worker under GST?
A freelancer generally provides services independently rather than working as a regular employee. A gig worker may accept short-term, task-based or platform-mediated assignments.
Examples include:
- Software developers and website designers.
- Graphic designers and video editors.
- Content writers, copywriters and translators.
- Digital marketers and social media managers.
- Business consultants and independent professionals.
- Virtual assistants and online tutors.
- Photographers and independent creative professionals.
- Workers accepting assignments through digital platforms.
GST treatment depends on the actual supply and business arrangement. Receiving freelance income does not by itself establish whether registration is compulsory. The relevant provisions and exemptions must be examined for the person's circumstances.
Is GST registration mandatory for freelancers in India?
GST registration for a freelancer is generally examined under Section 22 of the Central Goods and Services Tax Act, 2017, together with applicable exemptions and compulsory-registration provisions.
General registration thresholds
Under Section 22, the general threshold for a supplier making taxable supplies is:
- ₹20 lakh: General threshold for the specified States and Union Territories.
- ₹10 lakh: Threshold applicable in specified special-category State situations, subject to subsequent notifications and amendments.
These figures should not be treated as a universal rule for every freelancer. The applicable State, nature of supply, aggregate turnover and specific registration exemptions must be checked.
The relevant statutory provision is Section 22 of the CGST Act .
Does every freelancer have to register after crossing the threshold?
A registration decision must also consider Section 24, which specifies categories of persons required to register compulsorily, and exemptions issued under the GST law.
Some categories of inter-State service providers and other specified suppliers may qualify for exemptions. Therefore, a freelancer should not decide registration liability using the turnover figure alone.
Review the CBIC GST legal resources and the relevant notifications before making a registration decision.
How is aggregate turnover calculated for freelancers?
GST registration thresholds are based on aggregate turnover, not simply the profit earned by a freelancer or the amount received in one bank account.
Section 2(6) of the CGST Act defines aggregate turnover on an all-India basis for persons having the same PAN. It broadly includes:
- Taxable supplies.
- Exempt supplies.
- Exports of goods or services.
- Inter-State supplies.
The calculation excludes GST taxes and certain specified categories, including inward supplies on which tax is payable by the recipient under reverse charge.
Example of aggregate turnover
Suppose an individual operates a freelance service business and has the following supplies during a financial year:
| Type of supply | Illustrative value |
|---|---|
| Illustrative aggregate turnover | ₹14,00,000 |
| Domestic freelance projects | ₹8,00,000 |
| Eligible export service supplies | ₹5,00,000 |
| Other exempt supplies | ₹1,00,000 |
This illustration assumes all listed amounts are supplies attributable to the same PAN and that the stated categories are correctly classified. The actual calculation must follow Section 2(6), including its exclusions.
Important: Export turnover is not automatically excluded merely because the client is outside India. Qualifying exports are included in the aggregate-turnover calculation.
GST on freelance services provided to clients in other States
A freelancer may work from one State and provide services to clients located in another State. This may constitute an inter-State supply depending on the applicable place-of-supply rules.
Section 24 of the CGST Act contains compulsory-registration provisions for specified categories of inter-State suppliers. However, Notification No. 10/2017–Integrated Tax provides an exemption for qualifying persons making inter-State taxable supplies of services up to the prescribed aggregate turnover limit.
The notification specifies an all-India aggregate-turnover limit of ₹20 lakh, with a ₹10 lakh limit for the specified special-category State situation described in the notification.
This is why a freelancer should not assume that providing services to a client in another State automatically requires GST registration.
Read Notification No. 10/2017–Integrated Tax before applying the exemption to a particular case.
GST rules for gig platforms and e-commerce operators
Freelancers may obtain work directly from customers or through online platforms. These arrangements can have different GST implications.
Direct freelance contracts
When a freelancer contracts directly with a customer, the freelancer's own registration liability, place of supply, nature of service and applicable exemption need to be examined.
Work received through an online platform
When a platform connects freelancers with customers, it is necessary to understand the platform's role:
- Does the platform merely connect the parties?
- Does the platform collect the customer's payment?
- Who is identified as the supplier in the contract and invoice?
- Is the service covered by a notification under Section 9(5)?
- Does Section 52 tax collection at source apply?
Section 9(5): tax liability for notified services
Section 9(5) allows the Government to notify specified categories of services supplied through an electronic commerce operator for which the operator is liable to pay GST as if it were the supplier.
This applies only to notified categories and should not be assumed to cover every freelance service offered through an online marketplace.
Section 52: tax collected at source
Section 52 deals with tax collection at source by an electronic commerce operator in specified circumstances, including where the operator collects consideration for taxable supplies made through it.
TCS collected by a platform and GST liability on the underlying service are separate concepts. A freelancer should check the platform statement and applicable GST provisions instead of treating every platform deduction as the final GST payable.
Official references: Section 52 of the CGST Act and CBIC Sectoral FAQs on e-commerce operators .
GST on freelance income from foreign clients
Indian freelancers often work with customers based in the United States, United Kingdom, Canada, Australia, Europe and other countries.
A service supplied to a foreign customer may qualify as an export of services. However, receiving payment in foreign currency or having a foreign customer is not sufficient on its own.
Five conditions for export of services
Section 2(6) of the Integrated Goods and Services Tax Act, 2017 requires all five conditions to be satisfied:
- The supplier of the service is located in India.
- The recipient of the service is located outside India.
- The place of supply of the service is outside India.
- Payment is received in convertible foreign exchange or in Indian rupees wherever permitted by the Reserve Bank of India.
- The supplier and recipient are not merely establishments of a distinct person under the applicable statutory explanation.
All five conditions must be satisfied for the supply to qualify as an export of services.
The place-of-supply analysis is particularly important. Section 13 of the IGST Act contains rules for services where either the supplier or recipient is located outside India. Some categories have specific rules that differ from the general recipient-location rule.
Important issue: intermediary services
A freelancer who supplies services on their own account should not automatically be classified as an intermediary. However, a person who arranges or facilitates a supply between two or more parties may need to examine the intermediary definition and related place-of-supply provisions.
This distinction can affect whether the service qualifies as an export. Review the actual contract, scope of work and responsibilities before deciding.
Official references: GST Council material discussing export-of-services conditions and intermediary services and IGST Act, Section 16: Zero-rated supply .
What is LUT in GST and when is it required?
A Letter of Undertaking (LUT) is a prescribed undertaking that an eligible registered person may furnish to export goods or services without payment of integrated tax, subject to the applicable conditions.
LUT is relevant to a registered exporter choosing the export-without-payment-of-IGST route. It is not a universal registration requirement for every person who receives money from a foreign customer.
When should a freelancer examine LUT?
- The freelancer is registered under GST.
- The supply qualifies as an export under the IGST Act.
- The freelancer intends to export without payment of IGST under the applicable LUT procedure.
What should be checked before filing LUT?
- GST registration status and details.
- Whether the supply qualifies as an export.
- Applicable financial-year LUT requirements.
- Current GST Portal filing instructions.
- Invoice and export documentation.
Rule 96A of the CGST Rules and the applicable GST Portal procedure should be checked before filing.
Do not assume that every overseas payment is automatically covered by LUT or that LUT alone proves export eligibility.
For permitted INR export receipts, see the GST Council's official material on export-of-services payment conditions .
GST rates on freelance services in India
GST rates depend on the classification and description of the actual service. A professional's job title alone does not establish the applicable SAC or GST rate.
Some professional, technical and business services under the relevant residual service classifications may attract an 18% total GST rate. However, specific services may have separate classifications, rates or exemptions.
Freelancers should verify:
- The actual service being supplied.
- The applicable Service Accounting Code (SAC).
- The relevant GST rate notification.
- Whether any exemption or special condition applies.
- Whether the supply is intra-State, inter-State or an export.
For the official rate information, consult the CBIC GST Goods and Services Rates page .
Note: Do not automatically apply 18% to every content-writing, graphic-design, consulting, software-development or virtual-assistant assignment. Verify the service classification first.
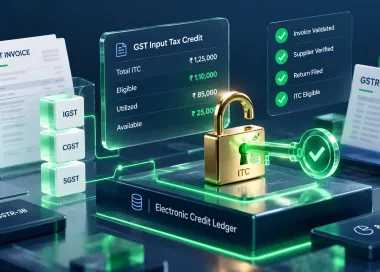
Input Tax Credit (ITC) for freelancers
A GST-registered freelancer may be eligible to claim Input Tax Credit on qualifying business purchases. However, registration does not make every purchase eligible for credit.
Examples of expenses to review for ITC eligibility
- Laptops and computer equipment.
- Business-use software subscriptions.
- Cloud hosting and eligible online services.
- Office equipment and furniture.
- Business-use internet and communication services.
- Professional tools and equipment.
Important conditions for claiming ITC
Section 16 of the CGST Act contains the eligibility conditions for taking ITC. These include, among other requirements:
- The recipient must be a registered person entitled to claim the credit.
- The goods or services must be used or intended to be used in the course or furtherance of business.
- The recipient must possess the prescribed tax invoice or other valid tax-paying document.
- Applicable supplier-reporting, tax-payment and return-filing conditions must be satisfied.
- Restrictions and blocked-credit provisions must be checked.
Section 17 restricts or apportions credit in specified situations, including mixed business and personal use and exempt supplies.
Example: laptop purchased for freelance work
Suppose a GST-registered freelancer buys a laptop for ₹1,00,000 plus GST. The GST component should not be claimed automatically.
The freelancer must check the invoice, business-use proportion, applicable ITC conditions and any relevant restriction. If the laptop is used partly for personal purposes, the eligible credit may need to be restricted accordingly.
Official references: Section 16: Eligibility and conditions for ITC and Section 17: Apportionment and blocked credits .
Documents required for GST registration by freelancers
The documents required depend on the applicant's business constitution, address, authorised signatory and the registration details requested by the GST Portal. There is no single document list that applies identically to every freelancer.
Common information and documents to prepare
- PAN details of the applicant or business, as applicable.
- Identity and address details of the proprietor or authorised person.
- Photograph and contact details, where requested.
- Proof of the principal place of business.
- Constitution documents, where applicable.
- Authorisation or board/partner documents, where applicable.
- Bank account information and supporting proof, as required.
Address proof for a home-based freelancer
A freelancer working from a rented or family-owned property should select the appropriate premises category and provide the supporting documents required for that situation.
Depending on the circumstances and portal requirements, this may involve a rent or lease document, ownership evidence, a consent letter or other supporting proof.
Do not upload a generic NOC or address document without checking that it is appropriate for the selected premises category.
Start the application through the official GST Portal and follow the live registration instructions.
GST 30-day bank account rule for freelancers
Rule 10A of the CGST Rules deals with furnishing bank account details after registration.
A registered person covered by Rule 10A, other than persons registered under Rule 12 or Rule 16, must furnish bank account details within:
- 30 days from the date of grant of registration; or
- Before furnishing outward supply details under Section 37 in GSTR-1 or using the Invoice Furnishing Facility (IFF);
Whichever is earlier.
This means the deadline is not always the 30th day. A taxpayer intending to furnish GSTR-1 details or use IFF earlier must consider the earlier filing event.
Rule 10A was amended by Notification No. 38/2023-Central Tax dated 4 August 2023.
Read the official Rule 10A text .
GST return filing for freelancers
Once registered, a freelancer must follow the return and payment requirements applicable to their taxpayer category and GST registration.
Regular taxpayers commonly deal with:
- GSTR-1: Statement of outward supplies.
- GSTR-3B: Summary return and payment of applicable tax liability.
The applicable filing frequency and due dates depend on the taxpayer's category, return scheme and any notified extensions. Check the current GST Portal calendar rather than relying on a fixed date from an older article.
QRMP scheme for eligible small taxpayers
The Quarterly Return Monthly Payment (QRMP) scheme allows eligible taxpayers to file GSTR-1 and GSTR-3B quarterly while making tax payments monthly.
GST Portal guidance states that eligibility generally requires PAN-based aggregate annual turnover of up to ₹5 crore in the current financial year and the preceding financial year, where applicable, along with filing the last due GSTR-3B return.
QRMP is not automatically available to every freelancer. The taxpayer must satisfy the scheme conditions and be eligible for the relevant return category.
Official reference: GST Portal QRMP scheme FAQs .
Practical GST examples for freelancers and gig workers
Example 1: Freelance designer serving local clients
A designer provides services to customers in the same State. The registration test should consider the applicable aggregate-turnover threshold, the nature of the supply and any other relevant registration provisions.
If the designer is below the applicable threshold and no compulsory-registration provision or other rule applies, registration may not be required solely because the person works independently.
Example 2: Freelancer serving a client in another State
A developer works from Rajasthan and provides software services to a business in another State. The developer should examine the place-of-supply rules and the exemption under Notification No. 10/2017–Integrated Tax before concluding that registration is compulsory.
Example 3: Indian freelancer serving a foreign customer
A content writer in India supplies work to a customer outside India and receives payment in foreign currency. The writer must check all five export-of-services conditions, including the place of supply.
If the supply qualifies as an export, it is treated as a zero-rated supply under the IGST Act. Registration and LUT requirements must be assessed separately.
Example 4: Gig worker accepting assignments through a platform
A worker receives assignments through an online platform. The worker should check the contract, identify the actual supplier, understand who collects the customer's payment and determine whether the service is covered by a notified Section 9(5) category or Section 52 TCS provisions.
The tax treatment should be determined from the actual platform arrangement rather than assuming every platform transaction follows the same rule.
Common GST mistakes freelancers should avoid
- Using profit instead of aggregate turnover: GST registration thresholds are based on aggregate turnover under the law, not simply net profit.
- Ignoring inter-State exemptions: Do not assume every inter-State service automatically requires registration.
- Treating every foreign payment as an export: Verify all five statutory export conditions.
- Filing LUT without checking eligibility: LUT is relevant to the specified registered-exporter route, not every overseas payment.
- Claiming ITC on every purchase: Check business use, invoice conditions and blocked-credit restrictions.
- Ignoring platform deductions: Understand the difference between GST liability, TCS and platform service charges.
- Missing bank account compliance: Check the Rule 10A deadline and applicable filing event.
- Using outdated filing dates: Confirm current return due dates and portal notices.
Frequently asked questions about GST for freelancers
01 Is GST registration mandatory for all freelancers in India?
No. Registration depends on aggregate turnover, the applicable threshold, the nature and location of supplies, compulsory-registration provisions and applicable exemptions.
02 What is the general GST registration threshold for freelancers?
Section 22 provides a general threshold of ₹20 lakh and a ₹10 lakh threshold for specified special-category State situations. The exact applicability must be checked with the relevant notifications and exemptions.
03 Does a freelancer have to register for GST when working with an out-of-State client?
Not necessarily. Notification No. 10/2017–Integrated Tax provides a threshold-based exemption for qualifying persons making inter-State taxable supplies of services. Check the notification and the specific facts before deciding.
04 Is GST applicable to income received from foreign clients?
Services supplied to foreign customers may qualify as exports if all five conditions under Section 2(6) of the IGST Act are satisfied. Foreign currency payment alone is not enough.
05 Do all freelancers need to file LUT?
No. LUT is relevant to eligible registered persons who choose to export without payment of IGST under the prescribed route. It is not a universal filing requirement for every freelancer receiving overseas payments.
06 Is the GST rate always 18% for freelance services?
No. The applicable rate depends on the actual service classification, SAC and relevant rate notification. Verify the classification before charging GST.
07 Can freelancers claim ITC on laptops and software?
Eligible registered freelancers may claim ITC when the statutory conditions are met. Business use, valid documents and restrictions under Sections 16 and 17 must be considered.
08 What is the GST 30-day bank account rule?
Rule 10A generally requires covered registered persons to furnish bank account details within 30 days from registration or before furnishing GSTR-1/IFF outward supply details, whichever is earlier. Rule 12 and Rule 16 registrations are excluded.
09 Can freelancers use the QRMP scheme?
Eligible registered taxpayers may use QRMP if they satisfy the turnover and return-filing conditions. The scheme allows quarterly returns with monthly tax payments.
10 Does a gig platform always pay GST instead of the freelancer?
No. Section 9(5) applies to notified categories of services supplied through an electronic commerce operator. Other platform arrangements may have different GST and TCS treatment.
11 What documents should a freelancer prepare for GST registration?
Common information includes PAN, identity and address details, proof of business premises and applicable constitution or authorisation documents. The exact requirements depend on the applicant and premises category shown on the GST Portal.
12 Where can freelancers verify current GST rules?
Freelancers can consult the CBIC Tax Information Portal, official GST Portal user guides and applicable government notifications and circulars.
Official government sources and legal references
The following primary and official government resources support the principal GST explanations in this guide. Readers should check the latest applicable amendments, notifications and portal instructions before acting.
- CGST Act, Section 22 – Persons liable for registration: CBIC Tax Information Portal
- Notification No. 10/2017–Integrated Tax – Inter-State services exemption: Official notification PDF
- CGST Act, Section 16 – ITC eligibility and conditions: CBIC Tax Information Portal
- CGST Act, Section 17 – Apportionment and blocked credits: CBIC Tax Information Portal
- IGST Act, Section 16 – Zero-rated supplies: CBIC Tax Information Portal
- CGST Act, Section 52 – Collection of tax at source: CBIC Tax Information Portal
- CBIC Sectoral FAQs – E-commerce operators: CBIC official FAQs
- CGST Rules, Rule 10A – Bank account details: CBIC Tax Information Portal
- GST Portal QRMP FAQs: Official GST Portal user guide
- GST rates for goods and services: CBIC GST rate information
- GST Portal: Official GST Portal
- GST Council material on export-of-services conditions: GST Council official website
Need help with GST compliance?
Freelancers and independent professionals may need help with GST registration, return filing, export documentation, ITC reconciliation or responding to a GST notice.
The correct compliance approach depends on the nature of the service, turnover, customer location and registration status.
Quick Tax Regime Estimator (FY 2025-26)
Simulate estimated tax liability under the New vs Old Tax Regime with standard salary deductions.
New Tax Regime
₹ 85,800
Includes ₹75k Standard Deduction & 4% CessOld Tax Regime
₹ 1,17,000
Assumes standard 80C + 80D claimedWas this guide helpful?
EasyTax • Trusted by 10,000+ Clients
GST Return Filing & Compliance
Timely GSTR-1 & GSTR-3B filing, 100% ITC matching and department notice defense by certified GST experts.