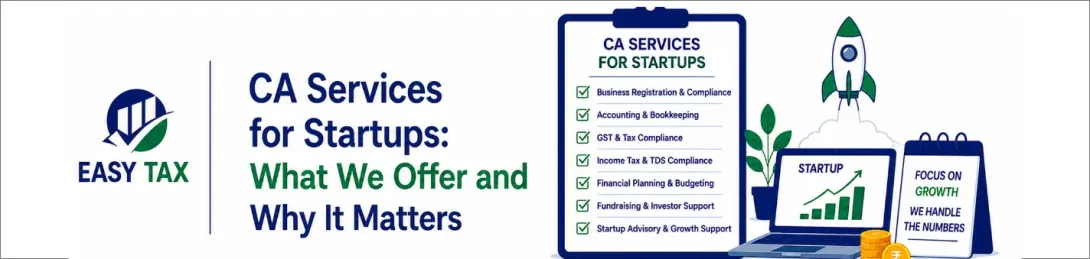
Ca Services for Startups: What We Offer and Why It Matters
Startup & CA
CA Services for Startups in India: What Founders Need and Why It Matters
From choosing a business structure to managing accounts, GST, tax deductions and investor reporting, a Chartered Accountant can help a startup build reliable financial processes as it grows.
Quick answer CA services for startups may include entity-setup support, bookkeeping, financial statements, tax-return preparation, GST and TDS compliance, payroll coordination, management reporting, funding-readiness support and Virtual CFO services. The right scope depends on the startup’s legal structure, transactions, registrations, stage and applicable law. Not every service or tax benefit applies to every startup.
Building a startup involves more than developing a product and finding customers. Founders also need dependable records, a suitable legal structure, visibility over cash flow and a process for meeting obligations that apply to their business. These responsibilities become harder to manage as the business hires people, invoices customers, raises capital or expands into new states.
A Chartered Accountant (CA) can help founders understand those requirements, set up repeatable finance processes and make better-informed decisions. A CA does not replace the founder’s responsibility for approvals, records or statutory filings; instead, the engagement should define who prepares, reviews, authorises and submits each item.
What CA services can include for a startup
“Startup CA services” is not one fixed package. A founder may need a one-time incorporation assignment, recurring accounting support or ongoing financial leadership. Agree the scope in writing before work begins.
| Service area | Typical work | Why it matters |
|---|---|---|
| Business setup | Compare entity structures, coordinate incorporation or registration, and organise initial records. | Creates a suitable legal and administrative foundation. |
| Bookkeeping | Record sales, expenses, receipts, payments, assets and liabilities. | Gives founders a reliable view of cash and performance. |
| Tax compliance | Assess applicable income-tax, advance-tax, TDS/TCS and return obligations. | Reduces avoidable errors and missed filing responsibilities. |
| GST support | Assess registration applicability, maintain reconciliations and prepare applicable returns. | Helps keep tax invoices, returns and books consistent. |
| Financial reporting | Prepare management reports, budgets, cash forecasts and financial statements. | Supports operating decisions and external review. |
| Funding readiness | Organise financial information, projections, reconciliations and due-diligence schedules. | Makes financial information easier for investors and lenders to assess. |
| Virtual CFO | Support planning, performance reviews, controls and finance-team processes. | Adds senior finance input without necessarily hiring a full-time CFO. |
Why startups use CA support
To choose and maintain an appropriate structure
The right structure depends on founder arrangements, liability preferences, ownership plans, funding expectations, regulatory obligations and ongoing administration. A Private Limited Company, LLP, registered partnership and other structures have different legal consequences. A CA can help model financial and tax implications, while legal advice may also be needed for shareholder, founder, intellectual-property or contract matters.
To build dependable financial records
Good records help founders understand runway, margins, outstanding receivables, vendor commitments and the cost of acquiring customers. They also make it easier to respond to tax, lender, investor and statutory information requests.
To identify obligations before they become urgent
Registration and filing obligations depend on the entity, turnover, transactions, employees, location and other facts. A compliance calendar should be prepared for the particular startup rather than copied from a generic list.
To make decisions using current numbers
Cash-flow forecasts, budgets and monthly management accounts can help a founder decide when to hire, invest in inventory, change pricing or raise capital. Reports are useful only when the underlying records are complete and reconciled.
Which services matter at each startup stage?
| Stage | Questions to resolve | Potential CA support |
|---|---|---|
| Idea and validation | Which structure fits the founders? What are the expected costs and funding plans? | Structure comparison, basic financial model and setup planning. |
| Incorporation | What registrations, documents, authorisations and opening records are needed? | Coordination of incorporation support and initial accounting setup. |
| First customers | How should invoices, receipts, expenses and indirect-tax applicability be handled? | Bookkeeping, invoice review, GST applicability assessment and tax process setup. |
| Hiring and scale-up | Which payroll, withholding, reporting and internal controls apply? | Payroll coordination, TDS review, monthly reporting and cash-flow monitoring. |
| Fundraising | Can the startup explain its revenue, costs, liabilities, ownership and forecasts? | Financial due-diligence preparation, reconciliations and investor reporting support. |
| Expansion | Do new locations, products, contracts or cross-border transactions change obligations? | Periodic compliance review, budgeting and finance-process design. |
Business structure, incorporation and startup recognition
Founders should choose a structure after considering ownership, liability, governance, funding plans, tax treatment and ongoing compliance. The choice should not be made solely because one structure is commonly used by other startups.
Company incorporation
For a company, the Ministry of Corporate Affairs’ SPICe+ process is the relevant incorporation route. The MCA instruction kit describes SPICe+ Part A for name reservation and Part B for incorporation information, with linked services and supporting documents. The exact filing requirements and portal workflow should be checked at the time of filing.
For an LLP or partnership, the applicable registration process is different. Do not use company incorporation forms as a universal checklist for all business structures.
DPIIT startup recognition is a separate assessment
DPIIT recognition under the Startup India framework is not the same thing as incorporating a company, registering an LLP or obtaining a GST registration. Eligibility is determined under the applicable notification and current Startup India process. The official Startup India guidance describes eligible entity forms and conditions relating to age, turnover, innovation or scalability, and restrictions involving reconstruction of an existing business.
Recognition should not be described as an automatic tax exemption. A startup must separately satisfy the conditions of the relevant tax provision and complete the required process. Check the current Gazette notification and official portal before advising on eligibility.
Accounting, bookkeeping and financial reporting
Accounting should begin with the first business transaction, not when the first tax return is due. A practical monthly close process may include:
- Recording sales, credit notes, purchases, expenses and reimbursements.
- Reconciling bank accounts, payment gateways, cash balances and loan accounts.
- Reviewing customer receivables, vendor payables and advances.
- Maintaining an asset register and tracking depreciation where applicable.
- Reconciling GST data and tax-withholding records with the books.
- Preparing a profit-and-loss statement, balance sheet and cash-flow view.
- Maintaining supporting invoices, contracts, approvals and payment evidence.
For companies, section 128 of the Companies Act, 2013 addresses books of account and related records. The specific statutory requirements for an LLP, partnership or other entity should be checked under its governing law and current rules. Management reports are useful internal tools; they do not replace statutory financial statements or audit requirements where those apply.
Income-tax compliance and tax planning
Income-tax compliance may involve maintaining business records, determining taxable income, evaluating advance-tax obligations, preparing returns, reviewing tax positions and responding to notices. The exact obligations depend on the taxpayer, entity, income, transactions and tax period.
Important law change from 1 April 2026
India’s Income-tax Act, 2025 applies from 1 April 2026. Earlier periods and transactions may continue to be governed by the Income-tax Act, 1961 under the applicable transition provisions. For advice, filings and withholding, identify the relevant period and transaction date before quoting a section number.
Startup deduction: recognition is not enough
The Income-tax Act, 2025 contains a deduction provision for eligible startups in section 140, subject to statutory conditions. Do not assume that every newly incorporated business or every DPIIT-recognised startup qualifies. The entity’s formation, business activity, approval/recognition, commencement, claim period and audit/documentation requirements must be checked against the current section, rules and official instructions.
Tax planning should mean applying the law to the startup’s actual facts, not promising a guaranteed tax saving. A responsible adviser should explain eligibility, assumptions, documentation, commercial consequences and the risk that a position may be challenged.
GST registration, returns and reconciliations
GST registration is not automatically required merely because a business describes itself as a startup. Applicability depends on the CGST Act, relevant State or Union Territory provisions, turnover and supply-related conditions, compulsory-registration provisions, exemptions and notifications. Inter-State supplies, e-commerce, reverse charge and other facts can affect the analysis. Obtain a fact-specific assessment before registering or deciding not to register.
Where registered, a startup may need help with tax invoices, input tax credit documentation, outward-supply reporting, return preparation, payment reconciliation and responses to portal notices. Return frequency and forms depend on the taxpayer’s registration and applicable scheme.
The GST Portal’s GSTR-3B user manual explains the filing workflow and states that a normal taxpayer is required to file for each applicable tax period, including a nil return where applicable. The portal’s nil-return facility has its own conditions; a nil return should not be filed simply because there were no sales if other conditions or liabilities prevent nil filing.
Use the current GST law, rules, notifications and portal instructions for the relevant tax period. A professional reconciliation or health-check service should be described as such; do not call it a mandatory statutory “GST audit” unless that exact legal obligation applies to the taxpayer.
TDS, TCS, payroll and people costs
Startups making payments to employees, contractors, professionals, landlords or other payees may have withholding or reporting obligations. The trigger, rate, threshold, timing, form and exceptions depend on the nature of payment and the applicable law.
For transactions governed by the Income-tax Act, 2025 from 1 April 2026, the Income Tax Department explains that salary withholding is addressed in section 392 and other specified payments in section 393. For the transition, the Department’s guidance says the earlier of credit or payment determines which Act governs many TDS obligations. A payment or credit on or before 31 March 2026 may remain under the 1961 Act; one on or after 1 April 2026 may fall under the 2025 Act, subject to the applicable provision and facts.
Payroll support can include salary data review, employee declarations, withholding calculations, payslip coordination and reconciliation. Employers should also assess applicable labour, social-security and state-level requirements separately; this article does not attempt to list every employment obligation.
Fundraising readiness and Virtual CFO support
Investors and lenders may ask for historical financial statements, monthly management accounts, revenue reconciliations, cash forecasts, tax filings, material contracts, debt schedules and explanations of unusual transactions. A CA can help organise and reconcile the financial information and identify gaps before a diligence exercise.
Valuation, securities issuance, shareholder rights, investment agreements and regulatory approvals can involve company law, securities law and legal advice. A CA’s financial work should be coordinated with the startup’s legal counsel and other advisers where needed.
What a Virtual CFO engagement may cover
- Monthly financial performance and variance reviews.
- Cash runway, working-capital and scenario forecasts.
- Budgeting, unit-economics and pricing analysis.
- Finance policies, approval controls and reporting calendars.
- Board or investor reporting support.
- Finance-team hiring plans and process improvements.
Agree deliverables, meeting frequency, access controls, confidentiality, responsibility for approvals and escalation procedures in the engagement letter.
How to choose a CA for your startup
Ask prospective advisers practical questions before appointing them:
- Have they worked with businesses at a similar stage and with a similar legal structure?
- Who will perform the work, who will review it and who will communicate with the founders?
- Which recurring filings, reconciliations and reports are included in the engagement?
- What documents and approvals must the startup provide, and by when?
- How are urgent notices, missed information and changes in law handled?
- How are fees, government charges, out-of-scope work and timelines documented?
- What secure process is used for sharing bank, payroll, identity and tax information?
Ask for a written scope and a clear responsibility matrix. A service provider should not guarantee tax savings, funding, regulatory approval or a particular outcome.
Founder’s readiness checklist
Use this list to prepare for an initial finance and compliance review. It is a discussion aid, not a universal statutory document list.
- ☐ Confirm the legal structure, incorporation/registration records and ownership details.
- ☐ Gather PAN, TAN, GST registration details (if applicable) and portal access ownership.
- ☐ Collect bank statements, sales records, invoices, expense bills and contracts.
- ☐ Reconcile customer receipts, vendor payments, loans and founder transactions.
- ☐ Identify employees, contractors, payroll arrangements and withholding payments.
- ☐ Review GST registration applicability and the returns required for each period.
- ☐ Prepare an income-tax calendar based on the applicable Act and tax period.
- ☐ Check whether DPIIT recognition is relevant and whether separate tax-benefit conditions may be met.
- ☐ Prepare a cash-flow forecast and monthly reporting pack.
- ☐ Document who prepares, reviews, approves and files each compliance item.
Frequently asked questions
Does every startup need a Chartered Accountant?
There is no single rule that every business must appoint an external CA for every task. However, businesses may have statutory accounting, audit, tax and filing obligations depending on their structure and facts. Professional support can help founders identify and manage those responsibilities.
What are the most useful CA services for an early-stage startup?
Common starting points are structure selection, incorporation coordination, bookkeeping setup, cash-flow reporting and an assessment of applicable tax and registration obligations. The service mix should be tailored to the business.
Can a CA help with startup registration?
A CA can advise on financial and tax implications and may coordinate registration work within the agreed professional scope. Company, LLP and partnership registration processes differ, and legal advice may be needed for founder or ownership arrangements.
Does DPIIT recognition automatically provide an income-tax deduction?
No. Recognition and tax-deduction eligibility are separate questions. The startup must satisfy the conditions of the applicable income-tax provision and follow the required process.
Does every startup need GST registration?
No universal answer applies. Registration depends on turnover, supply type, location, compulsory-registration rules, exceptions and notifications. Assess the startup’s actual transactions under the current GST law.
What is a Virtual CFO?
A Virtual CFO is an outsourced or part-time finance leadership arrangement. The scope may include budgeting, cash-flow forecasting, management reporting, controls and strategic finance support.
Can a CA prepare a startup for fundraising?
A CA can help organise financial statements, forecasts, reconciliations and diligence schedules. Legal documentation, securities compliance and investment terms may require specialist legal and other professional advice.
Need finance and compliance support for your startup?
Discuss your entity structure, current records, registrations, reporting needs and growth plans with the EasyTax team. Ask for a written scope that identifies deliverables, responsibilities, timelines and fees before starting an engagement.
Official sources and further reading
Use the current version of the applicable law and official portal instructions for the relevant period. Portal manuals explain operational workflows; they do not replace the Act, rules or notifications.
- Income Tax Department — e-Filing portal (official legislation, rules, forms and guidance).
- Income Tax Department — TDS Compliance FAQs (transition guidance for the Income-tax Acts and withholding).
- Income Tax Department — Tax Payments FAQs (TDS/TCS and tax-payment guidance).
- Startup India — DPIIT Startup Recognition and Tax Exemption (recognition guidance; verify the current notification and eligibility).
- Ministry of Corporate Affairs — SPICe+ Instruction Kit (company incorporation workflow; confirm the latest portal instructions).
- Ministry of Corporate Affairs — Companies Act, 2013 (reference copy; check later amendments and current rules before relying on a provision).
- GST Portal — Create and Submit GSTR-3B (operational return-filing manual).
- GST Portal (current registration, returns and taxpayer services).
Disclaimer: This article is general educational information, not legal, tax, accounting or investment advice for a particular business. Applicability depends on the entity, transactions, location and relevant tax period. Laws, rules, notifications and portal procedures may change. Obtain advice based on the startup’s facts before acting.
EasyTax • Jaipur
Startup Registration & Compliance
Get DPIIT recognition, seed fund compliance & complete business registration handled by CA specialists.